
You Built Your Own Business.
Don't Let Insurance
Hold You Back.
Private health plans through Life, Health & Family Insurance - with rates locked until age 65 and first-dollar Association Membership coverage. Built for people who work for themselves.
The Insurance System Wasn't Built for You.
If you are self-employed, you already know this. You pay more, get less, and watch your premiums go up every single year. It does not have to be this way.
Premiums That Climb Every Year
ACA marketplace plans increase rates annually - often 10–20% - with no ceiling in sight. You absorb every increase alone.
No Employer to Split the Cost
W-2 employees get employer-subsidized coverage. You pay 100% out of pocket - and still end up with a high deductible.
Deductibles That Make Coverage Feel Useless
A $5,000 deductible means you are essentially uninsured for routine care. You pay premiums every month and still pay full price at the doctor.
Stuck Between Bad Options
Too much income for subsidies, not enough employees for group rates. Most self-employed people feel like the system was not built for them.
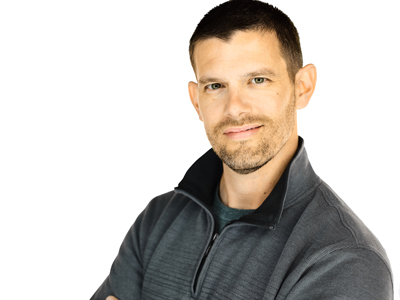
I Lived This Problem.
That's Why I Solve It.
After serving in the military - where health coverage was simply taken care of - I started my own photography business and a SaaS company. That is when I discovered the gap firsthand.
Locked into group policies with limited options, watching premiums climb every year, paying a massive deductible before coverage kicked in. I felt exactly what you are feeling right now.
That experience is exactly why I became a licensed insurance agent. I wanted to offer something I genuinely believe in - plans that actually take care of people, not just collect premiums.
“Insurance is something no one wants to pay for until they need it. My job is to bridge that gap with products I know will actually help people.”- Kirk M. Surber, Licensed Insurance Agent
Private Coverage Built for Business Owners.
Private plans paired with Association Membership first-dollar coverage give self-employed individuals and small business owners a real alternative to the ACA marketplace.
Rates Locked Until Age 65
Unlike ACA plans, your rate does not increase year over year. The premium you enroll at today is the premium you keep.
First-Dollar Coverage via Association Membership
The Association Membership layers first-dollar coverage onto your core plan - so benefits kick in immediately, before your deductible.
Private Plans - Not ACA
These are private health plans, not marketplace plans. More flexibility, more control, and no annual rate shock.
Deductible Gap Eliminated
Stop paying premiums and still paying full price at the doctor. The Association Membership fills the gap so your coverage actually works when you need it.
Covers Your Whole Team
Whether you are a solo operator or have a small team of 2–10, we have plans that work for your business structure.
Supplemental Coverage Available
Add dental, vision, accident, disability income, and more - all through one advisor who knows your full picture.
ACA Marketplace vs. Private Plan + Association Membership
| ACA Marketplace | Private Plan + Association Membership | |
|---|---|---|
| Annual Rate Increases | Yes - often 10–20%/yr | No - locked until age 65 |
| Deductible Before Coverage | $3,000-$6,000 typical | First-dollar via Association Membership |
| Plan Type | ACA Marketplace | Private - more flexibility |
| Employer Subsidy | None for self-employed | Tax-deductible premiums |
| Supplemental Add-ons | Limited | Dental, vision, disability & more |
| Coverage Stability | Changes annually | Consistent until age 65 |
If You Work for Yourself, This Is for You.
Not sure if this applies to you? Let's talk
What Self-Employed People Ask Me Most
Can I deduct my health insurance premiums as a self-employed person?
Yes - self-employed individuals can generally deduct 100% of health insurance premiums for themselves and their family. Consult your tax advisor for specifics to your situation.
How is a private health plan different from an ACA marketplace plan?
Private health plans are not ACA marketplace plans. The key differences are rate stability (locked until 65), first-dollar coverage options through the Association Membership, and more flexible plan structures.
What is first-dollar coverage and why does it matter for business owners?
First-dollar coverage means your benefits start from the very first dollar of a claim - before you hit your deductible. For business owners managing cash flow, this eliminates the risk of a large unexpected medical bill derailing your finances.
Can I cover my employees too?
Yes. Life, Health & Family Insurance offers plans for small businesses with 2 or more employees. We can structure coverage that works for your team and your budget.
What if I am healthy and rarely use insurance?
That is actually the best time to lock in your rate. Private plans reward healthy enrollees with lower premiums - and since your rate stays locked until 65, enrolling while healthy protects you from future increases.
How do I get started?
Schedule a free consultation with Kirk. We will review your current situation, walk through your options, and build a plan that fits your business and your budget - no pressure, no obligation.
Stop Overpaying for Coverage That Doesn't Work.
A free, no-pressure consultation is all it takes. We will look at your current situation, walk through your options, and build a plan that actually protects you - at a rate that stays locked until 65.